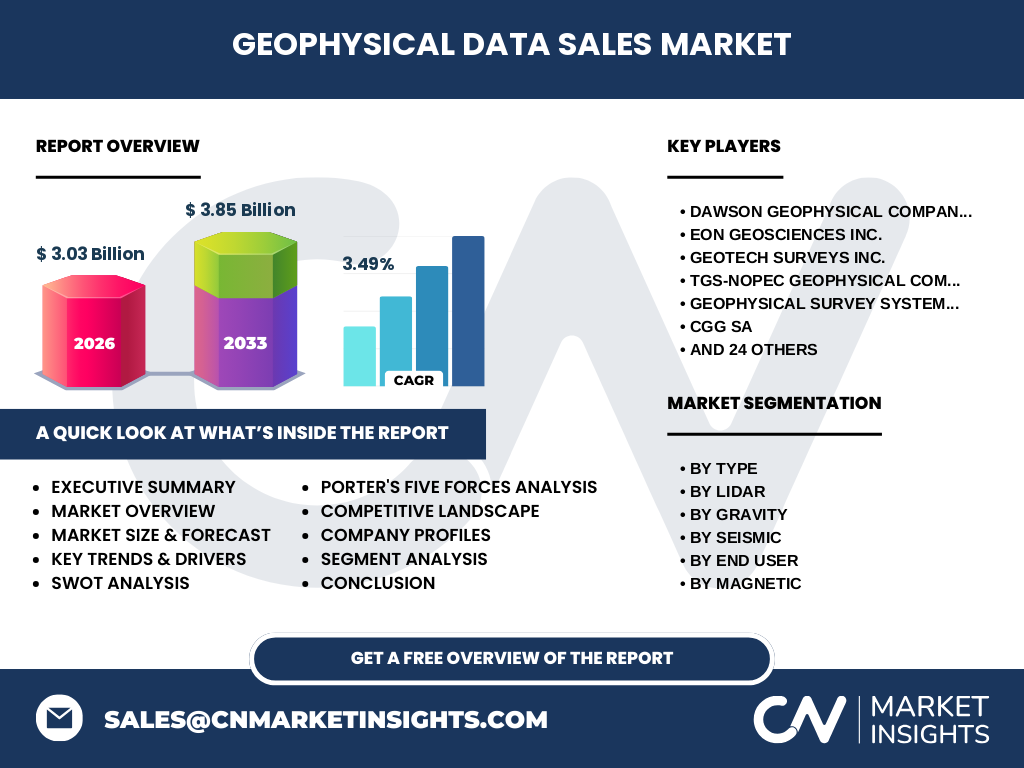
What is the market overview of the Geophysical Data Sales Market?
Our analysis indicates that the Geophysical Data Sales Market encompasses the commercialization of subsurface intelligence utilized across raw material extraction and infrastructure planning. The sector reaches a valuation of $3.03 Billion in 2026, driven by the critical need for high-fidelity subsurface mapping. Geophysical data acquisition and interpretation remain foundational for minimizing operational risks in complex geological formations overseen by regulatory bodies like the Department of the Interior.
Structural Growth Drivers and Market Restraints
The market is propelled by escalating demand for critical minerals and complex hydrocarbon exploration. Primary restraints involve high capital expenditure for offshore data acquisition and stringent environmental compliance mandated by agencies such as the EPA. Despite these hurdles, technological maturation in multi-component seismic and LIDAR surveys creates robust opportunities for specialized vendors operating in remote Arctic and deepwater basins.
The Shift Toward Advanced Subsurface Imaging Trends
Industry dynamics show a pronounced migration toward high-density Reflection Seismology and Airborne LIDAR to optimize asset development. Companies like TGS-NOPEC Geophysical Company ASA and CGG SA are leading the charge by monetizing multi-client data libraries. This trend directly benefits firms possessing advanced data processing capabilities, enabling operators to significantly reduce dry-hole risks in frontier exploration acreage.
COVID-19 Impact Analysis and Recovery Trajectory
The pandemic severely disrupted offshore acquisition schedules and delayed capital allocation for speculative multi-client surveys. However, the recovery trajectory is robust, underpinned by global energy security priorities and surging demand for transition minerals. Our research confirms that market normalization has accelerated digital transformation, forcing service providers to upgrade cloud-based data delivery models to service remote engineering teams efficiently.
Competitive Benchmarking in the Geophysical Data Sales Market
Market concentration is moderately high, anchored by tier-one players possessing vast multi-client data libraries. Major participants such as Schlumberger Limited, Fugro NV, and Petroleum Geo-Services ASA leverage integrated service models to dominate offshore basins. Meanwhile, specialized entities like Dawson Geophysical Company carve out profitable niches in onshore seismic data acquisition, intensifying competitive pressures across regional exploration hotspots.
Executive Summary of the Geophysical Data Sales Market
The Geophysical Data Sales Market is poised for steady expansion, advancing from $3.03 Billion in 2026 to $3.85 Billion by 2033 at a CAGR of 3.49%. Strategic consolidation and technological convergence around AI-driven data interpretation represent the primary themes shaping commercial success, requiring market participants to continually modernize their multi-client catalog offerings.
Market Forecast from 2027 to 2033
Driven by sustained exploration budgets and energy transition requirements, the sector will expand from its $3.03 Billion baseline in 2026 to reach $3.85 Billion by 2033. This growth trajectory reflects a steady 3.49% CAGR. Investment capital will increasingly flow toward high-resolution gravity gradient surveys and passive seismic monitoring applications designed to support carbon capture and storage initiatives.
Comprehensive Segmentation Analysis
The market breaks down across multiple vectors: By Type, covering Aerial-based and Land-based Survey; LIDAR, featuring Airborne LIDAR and Terrestrial LIDAR; Gravity, including Gravity Gradient and Measurement surveys; Seismic, encompassing Reflection, Refraction, Surface, and Borehole methodologies; End User, spanning Agriculture, Environment, Minerals and Mining, Oil and Gas, and Water Exploration; Magnetic, including Ground and Aeromagnetic variants; Services, dividing into Data Processing, Interpretation, and Acquisition; Technology, featuring Seismic, Magnetic, Gravity, Electromagnetics, LIDAR, and Ground Penetrating Radar; Electromagnetics, split into TDEM and FDEM; Ground Penetrating Radar, separating Shallow and Deep variants; and Other Technologies like ERT and MRI. Each segment plays a vital role in addressing specific subsurface resolution requirements.
Regional Market Analysis and Geographic Distribution
Geographic performance varies considerably, with North America leading due to mature shale plays and stringent environmental monitoring mandates. The Asia-Pacific region demonstrates high growth potential, propelled by offshore wind farm development and mineral exploration in Australia. Regional constraints such as local permitting hurdles and complex maritime boundary laws dictate localized acquisition strategies for key operators.
In-Depth Regional Review of Key Markets
North America dominates consumption, supported by extensive onshore data sales in the Permian Basin and deepwater Gulf of Mexico operations. Europe follows closely, driven by North Sea decommissioning projects and extensive marine geotechnical site investigations managed through agencies like OSPAR. Latin America and the Middle East represent high-value frontier markets where national oil companies actively procure high-end seismic datasets to optimize brownfield recovery.
Strategic Company Profiles
Industry leaders maintain distinct competitive moats through proprietary acquisition hardware and extensive multi-client libraries. CGG SA and TGS-NOPEC Geophysical Company ASA focus heavily on global multi-client library monetization. Simultaneously, engineering-focused firms like Ramboll Group A/S and CSA Global Pty Ltd. leverage specialized environmental and mining datasets to capture non-hydrocarbon revenue streams.
Porter's Five Forces Analysis of the Sector
Bargaining power of buyers remains moderate to high, as major energy conglomerates demand bespoke processing discounts. Threat of new entrants is low due to prohibitive capital expenditures required for modern ocean-bottom nodes and aircraft fleet maintenance. Rivalry among existing competitors is intense, compelling firms to continuously innovate in automated data interpretation software to protect operating margins.
SWOT Analysis of the Geophysical Data Sales Market
Strengths include proprietary multi-client libraries and advanced imaging algorithms. Weaknesses involve high exposure to cyclical commodity prices. Opportunities abound in geothermal exploration and carbon sequestration mapping. Threats center on geopolitical trade restrictions affecting specialized sensor hardware imports and regulatory pushback against offshore seismic blasting.
Value Chain Analysis from Raw Materials to End-Users
The value chain initiates with specialized electronic component manufacturers supplying geophones, hydrophones, and LIDAR sensors. Mid-chain activities involve acquisition contractors like BGP Inc. and SAExploration Holdings Inc. gathering raw field data. The downstream phase culminates in specialized data processing, interpretation, and commercial sales to end-users across mining, oil and gas, and civil engineering sectors.
Investment Insights and High-Potential Areas
Strategic capital should target technology providers specializing in low-environmental-impact acquisition and machine-learning-driven data processing. High-potential growth areas include hydrogeological surveys for water scarcity mitigation and baseline seismic monitoring for offshore carbon capture sites. Investors prioritizing ESG-aligned infrastructure will find robust growth in environmental and renewable energy sub-segments.
Conclusion and Key Takeaways
The Geophysical Data Sales Market demonstrates resilient fundamentals, scaling to $3.85 Billion by 2033 from $3.03 Billion in 2026. Success in this landscape requires balancing traditional hydrocarbon data monetization with emerging green energy applications, ensuring long-term relevance across diverse end-user segments.
Research Methodology for Baseline Estimates
Our baseline estimates are established by triangulating rigorous primary stakeholder interviews with C-level executives, exhaustive analysis of regulatory trade registry data, and secondary macroeconomic indicators. This multi-tiered validation approach ensures accurate market sizing and reliable forecasting across all regional and technological segments.
Scope of the Report and Coverage Parameters
This report covers global commercial data sales across all specified survey types, technologies, and end-user verticals from 2026 through 2033. Methodological limitations include potential delays in official government public land lease disclosures and proprietary private equity portfolio adjustments within unlisted survey contractors.
Recent Developments and Strategic Industry Moves
Recent market activity highlights strategic joint ventures focused on cloud-native subsurface data platforms. Key players are aggressively acquiring boutique processing firms to integrate artificial intelligence into standard seismic interpretation workflows. These moves reflect a broader industry push to reduce data delivery latency and enhance predictive accuracy for enterprise end-users.